

Why Getting an Insurance Quote Is the Smartest First Step to Protecting Your Family
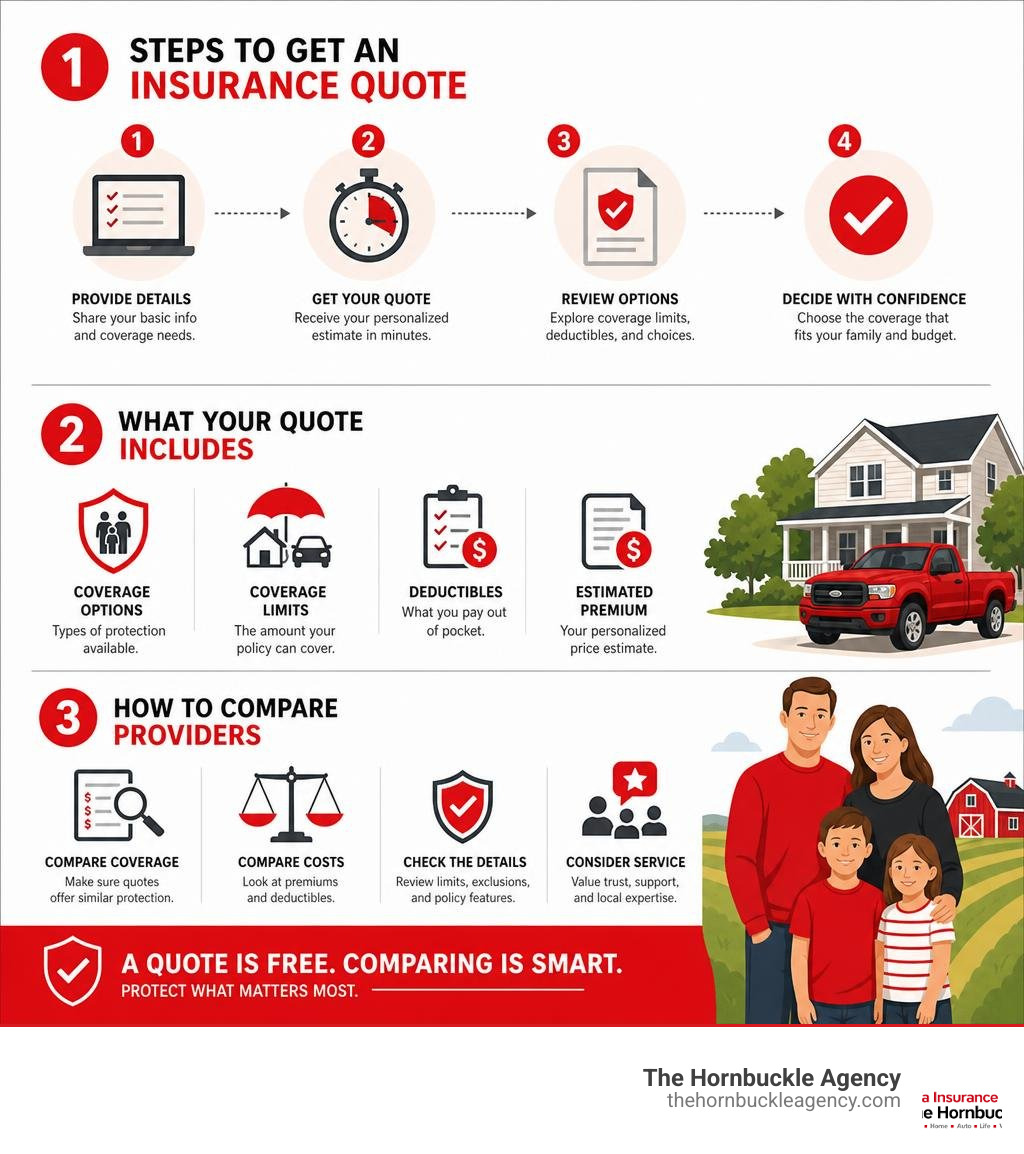
An insurance quote is a personalized estimate of what you’ll pay for coverage — and it’s completely free to get one.
Here’s what you need to know right away:
- What it is: A quote shows your estimated premium, coverage limits, and policy options before you commit to anything.
- How to get one: Answer a few questions about yourself, your vehicle, or your home — online or by phone — and you’ll receive an estimate, often in minutes.
- What it costs: Getting a quote is free and doesn’t obligate you to buy anything.
- Why it matters: Prices can vary significantly between providers for the exact same coverage. Comparing quotes is one of the simplest ways to save money.
- When to do it: Before buying a new policy, at each renewal, or after any major life change (new car, new home, marriage, teen driver).
For rural Alabama families, the stakes are real. Your home, your truck, your farm equipment, and your livelihood all need protection — and the wrong coverage, or paying too much for it, can hurt your financial security just as much as no coverage at all.
The good news? A little research goes a long way. Shoppers who compare quotes from multiple providers consistently find better rates and better coverage.
What is an Insurance Quote and How Does It Work?
At its core, an insurance quote is an offer. It is a calculation provided by an insurance company showing how much they estimate it will cost to cover your specific risks. When you request a quote, you are asking: “Based on who I am and what I want to protect, what will my premium be?”
The process relies heavily on a practice known as underwriting. Underwriters are the financial detectives of the insurance world. They analyze your risk profile using historical data, statistics, and mathematics to determine how likely you are to file a claim.
When you receive a quote, it is structured around several core components:
- Premium Estimates: The amount you will pay (usually monthly, semi-annually, or annually) to keep your policy active.
- Coverage Limits: The maximum amount the insurance company will pay out in the event of a covered loss.
- Policy Terms: The duration of the policy (typically six months for auto insurance and twelve months for home or farm policies) along with specific rules and exclusions.
It is important to remember that a quote is not a contract. It is a highly educated estimate. The final price can adjust slightly once the company officially runs your driving record, checks your property’s claims history, or verifies your credit background during the formal application process.
How Insurers Calculate Your Insurance Quote
Have you ever wondered why your neighbor might pay a completely different rate than you do, even if you drive similar trucks? Insurers calculate your insurance quote using a blend of risk assessment tools, actuarial tables, and localized variables.
Actuarial tables are vast databases that track risk patterns across millions of people over decades. Actuaries look at age, gender, type of property, and historical claims to determine probability. For example, statistics show that younger, less experienced drivers are statistically more likely to get into accidents, which is why their premium estimates are generally higher.
Furthermore, local rate factors play a massive role in Marshall County, AL. Insurers look closely at your ZIP code. They consider:
- Local weather patterns (such as Sand Mountain’s susceptibility to severe spring storms, tornadoes, or winter ice).
- Local accident rates on major roads like Highway 431.
- Regional construction costs, which dictate how much it would cost to rebuild a home in Albertville versus Boaz.
- The distance from your home to the nearest fire station or fire hydrant.
Key Information Needed for an Accurate Quote
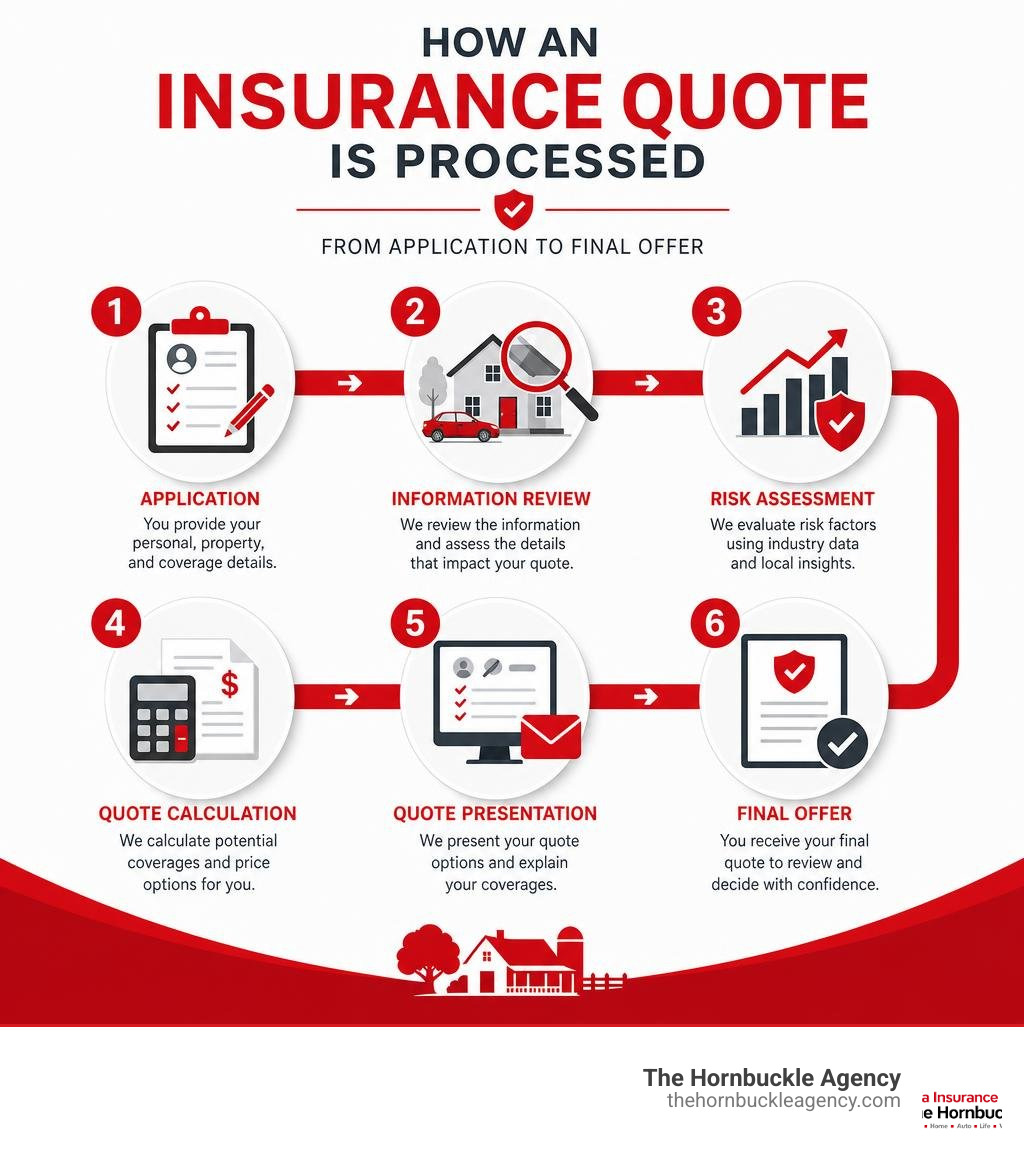
To get a highly accurate insurance quote rather than a vague ballpark figure, you need to provide precise information. If you guess or leave out key details, your final premium could end up being significantly higher than the initial estimate.
Here is the key information you should have on hand:
- Personal Details: Your full legal name, date of birth, marital status, and physical address. You will also need to list all licensed drivers or residents in your household who are 14 years of age or older.
- Driving History: Any accidents, speeding tickets, or violations over the past three to five years. Honesty is crucial here; insurance companies will pull your official Motor Vehicle Report (MVR) before finalizing the policy anyway.
- Property Details: For home or farm protection, you will need to know the age of the roof, the square footage, the type of heating and cooling systems, and whether you have safety features like smoke detectors, deadbolts, or a security system.
- Coverage History: Information about your current or previous insurance policies, including your current coverage limits and how long you have maintained continuous coverage without lapses.
Types of Insurance Policies and Key Cost Factors
Different assets require different types of protection. A standard policy is never a one-size-fits-all solution. Depending on where you live in Marshall County, you might need a combination of several specialized policies to protect your family and assets properly.
Auto, Watercraft, and Liability Coverage
For most families, protecting what moves them is the first priority. When seeking an insurance quote for your vehicles, you need to understand the different layers of protection.
- Auto Insurance: A solid Auto Insurance policy shields you from devastating financial loss if you are involved in a wreck on local roads. It typically includes bodily injury liability, property damage liability, collision coverage (for damage to your own vehicle), and comprehensive coverage (for non-collision events like animal collisions, hail, or theft).
- Watercraft Insurance: If you spend your weekends out on Lake Guntersville, standard home or auto policies won’t provide sufficient protection. A dedicated Watercraft Insurance policy covers physical damage to your boat, liability for bodily injury or property damage, and medical payments.
- Umbrella Insurance: Sometimes, the worst-case scenario exceeds your standard liability limits. An Umbrella Insurance policy acts as an extra safety net, providing an additional $1 million or more in liability coverage that kicks in after your primary auto or home liability limits are exhausted.
When shopping around, comparing different coverages helps you understand what is available in our community. Working with local representatives in Albertville or Guntersville allows you to see how different policies structure their coverage limits to fit your specific needs.
Home, Farm, and Commercial Protection
Protecting your stationary assets is just as critical as protecting your vehicles. Your home or business is likely your largest financial investment.
- Home Insurance: A standard Home Insurance policy covers your dwelling, detached structures, personal belongings, and personal liability. If you live in a manufactured home, you will want to look into specialized Manufactured Home Insurance designed specifically for the unique structural risks of mobile and modular homes.
- Farm Insurance: Marshall County is famous for its rich agricultural heritage, particularly poultry and livestock farming. A standard homeowners policy cannot handle the unique risks of a working farm. A specialized Farm Insurance policy covers your home, your barns, specialized farm machinery, livestock, and farm liability.
- Commercial Insurance: If you run a local business in downtown Boaz or Albertville, you need Commercial Insurance to protect your commercial property, general liability, commercial vehicles, and workers’ compensation.
- Specialized Institutional Coverage: Local community pillars also need protection. We offer specialized Church Insurance to protect houses of worship, their congregations, and their community outreach programs.
When evaluating your property and commercial needs, it can be useful to consult with local experts in Boaz who understand how to assess commercial and agricultural risks specific to our region.
Key Factors That Influence Your Premium Rates
When you request an insurance quote, the premium you are offered is determined by a unique combination of personal and environmental risk factors.
Here are the primary drivers behind your rate calculations:
- Your Driving and Claims History: A clean driving record and a history of zero home insurance claims will always net you the lowest rates. A single speeding ticket or an at-fault accident can cause premiums to rise.
- Your Credit History: In Alabama, insurance companies are legally allowed to use your credit-based insurance score to help determine your premium. Statistics show a strong correlation between credit health and risk management, meaning a higher credit score generally leads to lower insurance rates.
- Your Location: Living in areas prone to specific natural disasters (like windstorms on Sand Mountain) or areas with higher property crime rates can affect your property premiums.
- Your Chosen Deductible: Your deductible is the amount you agree to pay out of pocket before your insurance coverage kicks in. Choosing a higher deductible lowers your monthly premium, but you must ensure you have that cash set aside in case you ever need to file a claim.
Common Discounts to Lower Your Insurance Quote
While insurance is a necessary expense, you should never pay more than you have to. Fortunately, insurance companies offer a wide variety of discounts that can dramatically lower your insurance quote.
- Policy Bundling: This is often the single most effective way to save. You could save over $950 a year on car and home insurance when you bundle online or work with a local agent to combine your auto, home, or life policies under one roof.
- Safe Driver Discounts: If you have gone several years without an accident or ticket, you may qualify for substantial safe driving discounts.
- Good Student Discounts: If you have a teen driver on your policy who maintains a “B” average or a 3.0 GPA, most insurers will offer a discount to reward their responsibility.
- Multi-Vehicle Discounts: Insuring more than one vehicle on the same policy almost always qualifies you for a lower rate per vehicle.
- Safety and Security Features: Having anti-lock brakes, airbags, or anti-theft devices in your car, or smart home security systems and smoke alarms in your house, will reduce your rates.
| Policy Setup | Estimated Annual Premium | Potential Savings |
|---|---|---|
| Standard Auto + Home (Separate Companies) | $3,400 | $0 (No discount) |
| Bundled Auto + Home (Same Company) | $2,450 | $950 (Bundling Discount) |
| Bundled + Safe Driver + Good Student | $2,100 | $1,300 (Combined Discounts) |
How to Compare and Choose the Best Provider
When comparing insurance quotes, it is incredibly easy to fall into the trap of simply choosing the cheapest option. However, the true value of an insurance policy is only revealed when you actually have to use it. A cheap policy that doesn’t pay out when your home is damaged is the most expensive policy you can buy.
When choosing a provider, look at these three pillars:
- Financial Strength: Check the company’s financial ratings through independent agencies like A.M. Best. You want a company that has the financial backing to pay out large volumes of claims after a major local disaster.
- Customer Service: Look for a provider with a reputation for fast, fair claims processing. Having a local agent you can call directly is often much more reassuring than dealing with an automated phone tree during a stressful emergency.
- Coverage Details: Ensure you are comparing apples to apples. A cheaper quote might have much lower liability limits or a higher deductible than a slightly more expensive quote.
Steps to Get an Instant Online Quote
If you prefer to start your search online, getting a basic estimate can be quick and straightforward.
- Gather Your Documents: Have your driver’s license, vehicle identification number (VIN), and current policy declaration page handy.
- Use Reliable Tools: You can utilize online quote calculators and estimators to get a baseline idea of regional pricing.
- Customize Your Coverage: Don’t just accept the default minimum coverages. Adjust the sliders for liability limits and deductibles to see how they impact your monthly payment.
- Speak to a Local Expert: Once you have a digital estimate, have a local agent review it. A local agent can often spot missing discounts or coverage gaps that an online algorithm might overlook.
Understanding State-Specific Requirements
Every state has its own legal guidelines regarding insurance. In Alabama, the Mandatory Liability Insurance (MLI) law requires all motorists to carry a minimum amount of liability coverage to legally operate a vehicle.
The current minimum liability limits in Alabama are 25/50/25:
- $25,000 for bodily injury or death per person in an accident.
- $50,000 for total bodily injury or death per accident (if multiple people are hurt).
- $25,000 for property damage per accident.
While these are the legal minimums, they are rarely enough to protect you in a serious accident. If you cause a multi-car collision or damage a newer truck, the repair and medical bills can easily exceed $25,000. If your insurance limits are too low, the injured parties can sue you personally to recover the remaining balance, putting your home, savings, and future wages at risk. This is why we always recommend carrying limits well above the state minimums.
Frequently Asked Questions About Insurance Quotes
What is the difference between an insurance quote and an insurance policy?
An insurance quote is merely an estimate of what your premium might be based on preliminary information. It is not legally binding, and you do not have coverage yet. An insurance policy is a formal, legally binding contract that you sign, pay for, and put into effect. Once the policy is active, your coverage is officially bound.
Does getting an insurance quote affect my credit score?
No. When an insurance company checks your credit history to generate an insurance quote, they perform what is known as a “soft inquiry” (or soft pull). This does not affect your credit score in any way, unlike the “hard inquiries” that occur when you apply for a credit card, a car loan, or a mortgage.
How often should I shop around for new quotes?
We recommend reviewing your insurance coverage at least once a year, or whenever you experience a major life event. Getting married, buying a home, purchasing a new vehicle, adding a teen driver to your policy, or remodeling your property are all excellent times to request a fresh insurance quote to ensure your coverage matches your current life situation.
Conclusion
At the end of the day, an insurance quote is more than just a monthly price tag. It represents the financial shield that stands between your family and a devastating loss.
At The Hornbuckle Agency, we believe that insurance shouldn’t be a guessing game. As a local Alfa Insurance provider serving Albertville, Guntersville, Boaz, and all of Marshall County, AL, our mission is to provide personalized risk education. We don’t just want to sell you a policy; we want to help you understand exactly what you are protecting and why.
Whether you are looking to secure your family’s future with Life Insurance, protect your property with Home Insurance, or get a competitive rate on your vehicles, we are here to help guide you every step of the way.
Ready to see how much you could save while securing the peace of mind your family deserves? Get a personalized quote today or Contact Us directly to speak with a local agent who understands Sand Mountain and Marshall County life.
