

What Drivers in Albertville, AL Need to Know About Car Insurance
Finding the right car insurance in Albertville, AL comes down to a few key facts every local driver should know before shopping for coverage.
Quick answers for Albertville drivers:
| Question | Answer |
|---|---|
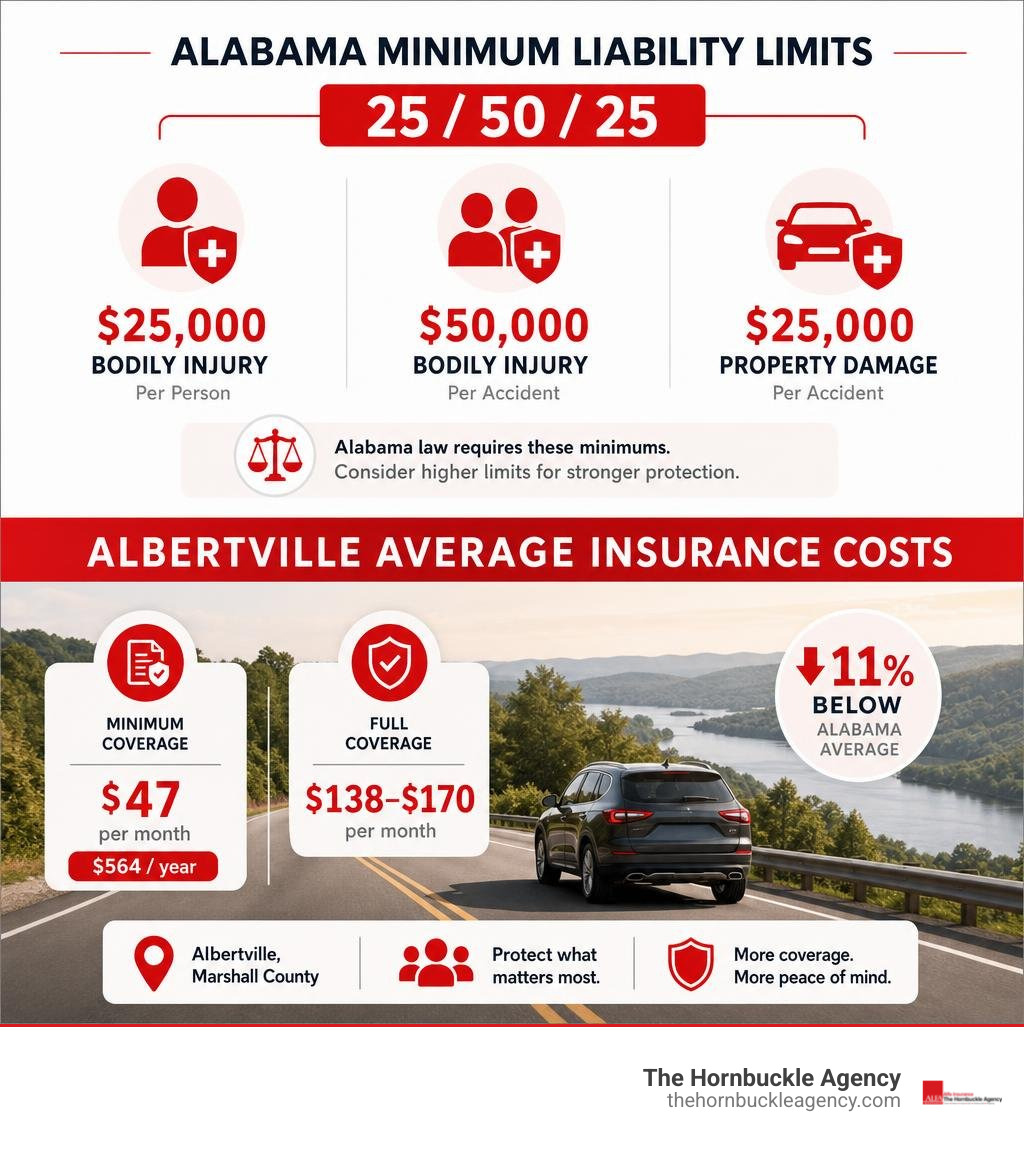
| Alabama minimum coverage | 25/50/25 liability limits |
| Average minimum coverage cost | ~$47/month ($564/year) |
| Average full coverage cost | ~$138–$170/month |
| Albertville vs. state average | ~11% below Alabama average |
| Uninsured drivers in Alabama | Over 19% of all drivers |
Alabama law requires every driver to carry at least $25,000 in bodily injury coverage per person, $50,000 per accident, and $25,000 in property damage liability. That’s the legal floor — not necessarily the protection your family needs.
Albertville sits in Marshall County, and local drivers actually pay less than most Alabamians — roughly $161 per month for full coverage, compared to the state average of $181. But cheaper rates don’t always mean the right coverage.
I’m Dustin Hornbuckle, owner of The Hornbuckle Agency and an Alfa Insurance provider based right here in Albertville — with nearly 18 years of experience helping Marshall County families find the car insurance in Albertville, AL that truly fits their lives and budgets. In this guide, I’ll walk you through everything you need to make a confident, informed decision.
Alabama Auto Insurance Requirements and Legal Framework
When we take our cars out on the roads of Marshall County, we are bound by state laws designed to protect everyone on the highway. Understanding these requirements is the first step toward establishing real financial protection. While buying the absolute bare minimum might keep you legal, it rarely keeps you safe from major financial loss.
To protect your hard-earned savings, it is crucial to understand how auto insurance works under Alabama’s unique legal framework.
Mandatory Minimum Liability Limits in Alabama
Alabama law dictates that every motorist must carry a minimum amount of liability coverage. This coverage is designed to pay for the damage and injuries you cause to other people in an accident; it does not pay for your own vehicle or your own injuries.
The state mandates what the industry calls the 25/50/25 limits:
- $25,000 bodily injury liability per person: The maximum amount your policy will pay for a single injured person’s medical expenses in an accident you caused.
- $50,000 bodily injury liability total per accident: The absolute limit your policy pays out for all injured parties combined in a single crash.
- $25,000 property damage liability per accident: The maximum amount available to repair or replace another person’s vehicle, mailbox, or property that you hit.
While these limits might have seemed sufficient years ago, consider modern medical and vehicle repair costs. If you cause a multi-car pileup on Highway 431 near the school zones, $25,000 in property damage will barely cover a fraction of a single new SUV.
Additionally, Alabama law requires carriers to offer you Uninsured/Underinsured Motorist (UM/UIM) coverage at limits of $25,000 per person and $50,000 per accident. While you can technically reject this coverage in writing, doing so is a massive financial gamble. Alabama consistently ranks among the states with the highest percentage of uninsured drivers—currently estimated at over 19%. This means nearly one out of every five vehicles you pass on your daily commute to Boaz or Guntersville has no insurance at all. If one of those drivers hits you, UM/UIM coverage is often your only practical path to recovery.
Pure Contributory Negligence and Coverage Lapses
Alabama is one of only four states in the country that still adheres to the strict legal rule of pure contributory negligence. Under this rule, if you are involved in an accident and are found to be even 1 percent at fault, you are completely barred from recovering damages from the other driver.
Because the legal system makes it incredibly difficult to collect from other drivers unless they are 100% to blame, having robust personal coverage—and meticulously documenting any accident—is vital. This legal reality is one of the reasons why insurance rates in Alabama remain relatively stable compared to states with highly litigious comparative fault systems, but it places a heavy burden on you to carry proper physical damage protection.
Furthermore, Alabama does not take insurance compliance lightly. The state utilizes an advanced electronic monitoring system to cross-reference registered vehicles with active insurance policies.

If a coverage lapse is detected, the consequences escalate quickly:
- Registration Suspension: The state will suspend your vehicle’s registration.
- Reinstatement Fees: You will face hefty fines to get your vehicle back on the road.
- SR-22 Requirement: Repeated lapses or driving without insurance can lead to mandatory SR-22 filings, which label you as a high-risk driver and skyrocket your premiums.
What is the Average Cost of Car Insurance in Albertville AL?
When looking for car insurance in Albertville, AL, understanding the local baseline costs helps you determine if you are getting a fair deal. Fortunately for those of us living on Sand Mountain, Marshall County rates are among some of the most competitive in the state due to our lower urban density and lower litigation rates compared to cities like Birmingham or Mobile.
To get a highly accurate estimate tailored to your age, vehicle, and driving record, you can use the 2026 Alabama Car Insurance Calculator: Estimate Your Monthly Rate | How Much To Insure .
Cost of Minimum vs Full Car Insurance in Albertville AL
In the 35950 ZIP code, premiums vary significantly depending on whether you choose state-minimum liability or a robust full-coverage policy.
| Coverage Level | Average Monthly Cost | Average Annual Cost | What It Typically Includes |
|---|---|---|---|
| Minimum Liability Only | $33 – $47 | $396 – $564 | 25/50/25 Bodily Injury & Property Damage |
| Full Coverage | $138 – $169 | $1,656 – $2,028 | Liability + Collision + Comprehensive ($500/ $1000 Deductibles) |
Note: These are average figures for a driver with a clean record in Albertville. Your actual rate will depend on your personal profile.
While minimum coverage is undeniably easier on the monthly budget, full coverage provides the physical damage protection necessary to repair your own vehicle if you hit a deer on a rural road or get caught in a sudden North Alabama hailstorm.
Key Factors Influencing Your Local Premium
Have you ever wondered why your neighbor pays a completely different rate for their car insurance than you do? Insurance companies do not use a one-size-fits-all pricing model. Instead, they use complex, proprietary rating systems to evaluate how likely you are to file a claim.
The primary factors that dictate your premium include:
- Your Credit Score: In Alabama, insurers are legally permitted to use credit-based insurance scores. Studies show a strong correlation between financial stability and safe driving habits, meaning a higher credit score directly translates to lower insurance premiums.
- Your Driving Record: A single speeding ticket can push your monthly rate up significantly, while a DUI or reckless driving charge can double or triple your costs.
- Age and Gender: Teen drivers (ages 16–19) face the highest rates in Albertville, often averaging over $500 per month due to their statistical lack of experience behind the wheel.
- Vehicle Model: The cost to repair your vehicle, its safety ratings, and its likelihood of theft all play a role in your rate.
- The “Switching” Myth: We have all seen the commercials claiming you will “save $500 by switching.” In reality, these claims are situational. Because every company weighs credit, age, and driving history differently, a carrier that is cheap for a 40-year-old married driver with excellent credit might be highly expensive for a 21-year-old with a speeding ticket.
How Local Traffic and Weather Affect Albertville Rates
Our local geography and daily routines directly impact what we pay for auto protection. Albertville is a bustling hub, and certain areas present higher risks than others.
- Traffic Bottlenecks: Commuting daily along U.S. Highway 431, especially near the busy retail corridors of Albertville Commons or during school pick-up hours near Albertville High School, exposes you to stop-and-go traffic where rear-end collisions are common. The intersection of Highway 431 and Highway 75 is another local hotspot for minor accidents.
- The Tourist Effect: From June to early October, we see a massive influx of tourist traffic heading toward Lake Guntersville. Navigating around boat trailers, RVs, and out-of-town drivers who are unfamiliar with our local roads increases the likelihood of an unexpected incident.
- North Alabama Weather: Sand Mountain is beautiful, but our weather can be incredibly severe. Heavy Southern rainstorms, flash flooding, damaging summer windstorms, hail, and the seasonal threat of tornadoes make comprehensive coverage a necessity, not a luxury. If a tornado throws a tree limb onto your parked car, only comprehensive insurance will pay to fix it.
How to Find Cheap Car Insurance in Albertville AL
While we never recommend sacrificing essential protections just to save a buck, there are highly effective, legitimate strategies you can use to secure affordable rates without leaving yourself financially exposed.
Strategies for Cheap Car Insurance in Albertville AL
If you want to drive down the cost of your car insurance in Albertville, AL, consider these actionable steps:
- Adjust Your Deductibles: One of the fastest ways to lower your monthly premium is to increase your physical damage deductibles. Moving your collision and comprehensive deductibles from $250 to $500, or from $500 to $1,000, can reduce your premium significantly. Just ensure you keep that deductible amount tucked away in a savings account in case you ever need to file a claim.
- Evaluate Older Vehicles: If you are driving an older, fully paid-off vehicle that has depreciated significantly, carrying collision and comprehensive coverage might not make financial sense. If the annual cost of the coverage exceeds 10% of the car’s total value, it might be time to drop down to liability and uninsured motorist coverage only.
- Keep Your Mileage Low: If your daily commute is short—perhaps you work right here in downtown Albertville or nearby Boaz—be sure to let your agent know. Low-mileage drivers often qualify for specialized rate reductions.
Policy Bundling and Available Discounts
The most powerful tool in your savings arsenal is policy bundling. By placing your auto coverage and your home insurance (or renters insurance) with the same carrier, you can instantly unlock multi-policy discounts that typically save you between 5% and 10% on both premiums. Bundling also simplifies your life by keeping your bills in one place and often opens the door to loyalty perks, such as single-deductible waivers if a storm damages both your home and your car simultaneously.
Other discounts we always encourage our neighbors to ask about include:
- Safe Driver Discounts: For maintaining a clean driving record free of accidents and moving violations.
- Good Student Discounts: If you have a high school or college student on your policy who maintains a “B” average or higher (a 3.0 GPA), most carriers will reward that responsibility with a lower rate.
- Defensive Driving Courses: Completing an approved defensive driving class can earn you an immediate discount on your liability coverages.
Understanding SR-22 Requirements and Optional Coverages
For drivers who have experienced a lapse in coverage, a DUI, or too many points on their license, the state of Alabama may require an SR-22 filing. It is important to clarify that an SR-22 is not actually a type of insurance; it is simply a form filed by your insurance company with the Alabama Department of Public Safety certifying that you carry the required liability limits. Carrying an SR-22 will naturally increase your rates, but maintaining continuous coverage and a clean record will eventually allow you to remove the filing and restore your standard rates.
Beyond the state-mandated minimums, we always advise looking into highly valuable optional coverages:
- Collision Coverage: Pays to fix your vehicle if you hit another car, a guardrail, or a tree.
- Comprehensive Coverage: Protects your car from non-accident hazards like animal collisions (very common in Marshall County’s rural areas), theft, vandalism, hail, and storm damage.
Frequently Asked Questions About Albertville Auto Insurance
Navigating the insurance landscape can feel overwhelming. Here are straightforward answers to some of the most common questions we hear from drivers in Albertville, Boaz, and Guntersville.
How do I get auto insurance quotes in Albertville?
Getting an accurate quote does not have to be a complicated chore. To streamline the process, we recommend gathering your driver’s license number, Social Security number, vehicle VIN, and current mileage before you reach out to an agent.
To explore the process of gathering and comparing your options step-by-step, take a look at our ultimate guide to auto insurance quotes.
While you can utilize online tools or check local directories, working with a local professional who understands Marshall County is always your best bet. A local agent can help you navigate the unique regional factors and ensure you are getting all the discounts you qualify for.
Does auto insurance follow the car or the driver in Alabama?
In Alabama, auto insurance typically follows the car, not the driver.
If you lend your truck to a friend to haul some pine straw from Boaz, and they get into an accident, your insurance policy acts as the primary coverage for the incident. This is known as permissive use. However, because your policy is on the line, you should be incredibly careful about who you allow behind the wheel of your vehicle. If the damages exceed your policy limits, both you and the driver could be held personally liable.
Why does my credit score affect my car insurance rate?
It might seem unfair that your financial history affects what you pay to drive, but actuarial data shows a clear link between credit scores and risk.
Insurers use a specialized “credit-based insurance score” to evaluate the probability of a policyholder filing a claim. Statistically, individuals who manage their credit responsibly tend to file fewer claims and practice safer driving habits. Improving your credit score over time is one of the most effective long-term strategies for lowering your insurance premiums.
Conclusion
At the end of the day, car insurance is about much more than just a piece of paper in your glove box to show a state trooper. It is about protecting your family, your hard-earned assets, and your peace of mind every time you pull out of your driveway.
At The Hornbuckle Agency, we pride ourselves on delivering personalized risk education. We do not believe in one-size-fits-all policies or high-pressure sales tactics. Instead, we take the time to sit down with our neighbors in Albertville, Guntersville, and Boaz to explain how their coverage works, identify hidden discounts, and build a protection plan that truly fits their lives.
To learn more about who we are and how we serve our community, visit our about page. If you are ready to experience the difference that local, personalized guidance makes, we invite you to contact us today.
Ready to protect what matters most? Get a personalized quote from The Hornbuckle Agency and let us help you cruise Sand Mountain with total confidence.
