
What Homeowners Insurance in Albertville, AL, Should Protect
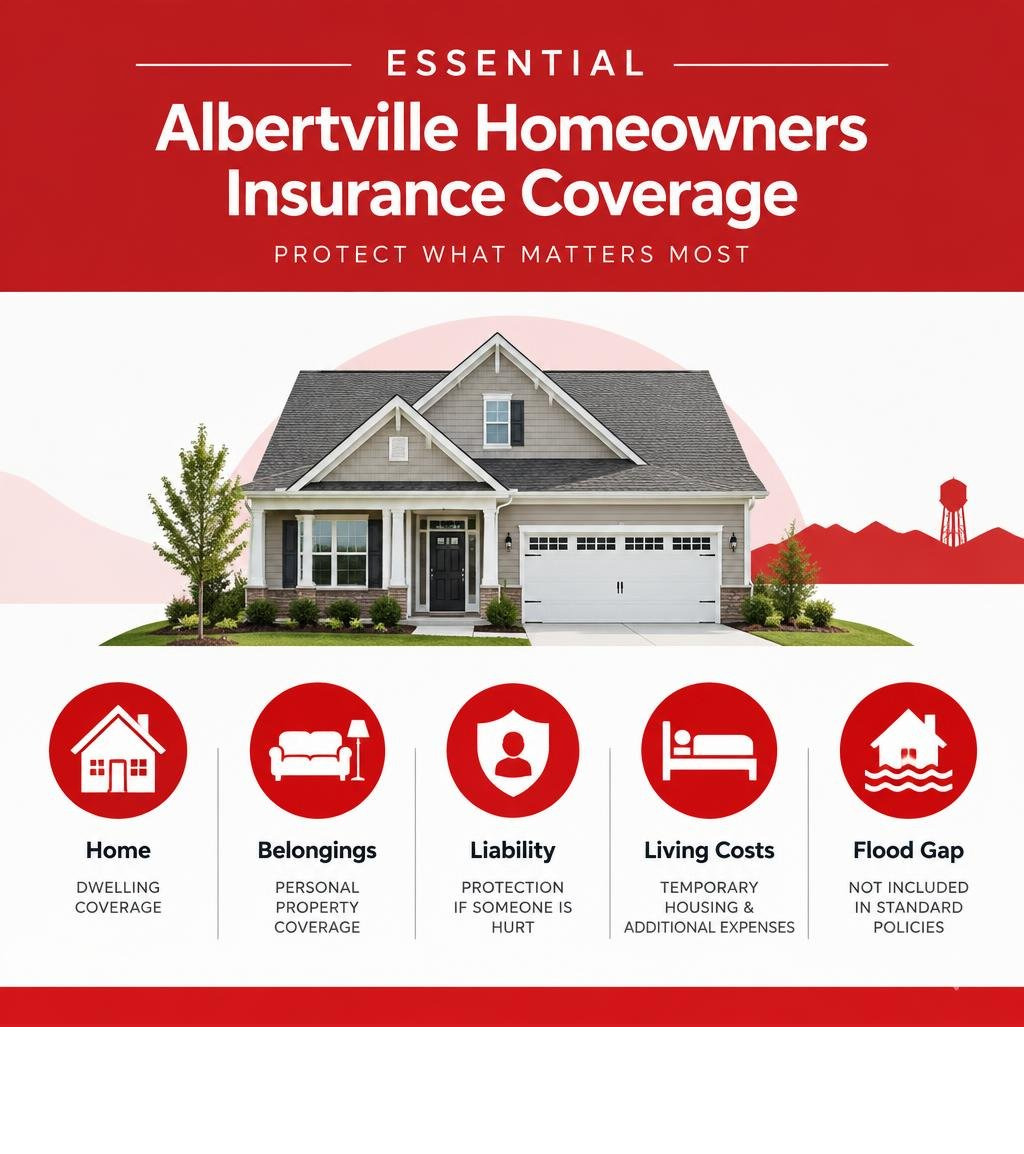
Homeowners insurance in Albertville, AL, typically covers your house, belongings, liability, and a place to stay if a covered loss makes your home unlivable. Check your wind and hail coverage, deductible, and dwelling limit before you buy or renew. Standard policies usually do not cover flooding, so ask about that gap if water could reach your property.
Understanding Homeowners Insurance in Albertville, AL: Core Coverages
Securing proper coverage for your home begins with understanding the essential protection layers built into a standard policy. A comprehensive policy safeguards both the physical structure you live in and the financial stability you have worked hard to build.
- Dwelling Coverage (Coverage A): This is the foundation of your policy. It covers the physical structure of your house, including the roof, walls, built-in appliances, and attached structures like garages or porches. Having adequate dwelling coverage ensures you can rebuild your home from the ground up if it is completely destroyed by a covered peril such as fire, lightning, or severe wind.
- Other Structures (Coverage B): Detached structures on your land—such as detached garages, storage sheds, fences, and gazebos—are protected under this section, usually set at a percentage of your dwelling coverage.
- Personal Property Protection (Coverage C): This covers the personal items inside your home, including furniture, electronics, clothing, and kitchen appliances. If your belongings are stolen or damaged in a covered incident, this section provides reimbursement.
- Loss of Use / Additional Living Expenses (Coverage D): If a severe storm or fire renders your property temporarily uninhabitable, loss of use coverage pays for temporary lodging, restaurant meals, storage units, and related living expenses while repairs are underway.
- Personal Liability (Coverage E): Liability protection defends you and covers legal and medical expenses if someone is accidentally injured on your property or if you accidentally cause property damage to someone else.
- Medical Payments to Others (Coverage F): This covers minor medical expenses for guests injured on your property, regardless of fault, helping to resolve smaller incidents quickly without litigation.
When structuring these protections, one of the most critical decisions involves choosing how your property is valued: Actual Cash Value (ACV) versus Replacement Cost Value (RCV).
| Feature | Actual Cash Value (ACV) | Replacement Cost Value (RCV) |
|---|---|---|
| Depreciation Deduction | Yes (factors in age and wear) | No (pays to replace with new item) |
| Out-of-Pocket Expense at Claim | Higher | Lower |
| Typical Annual Premium | Lower | Moderately higher |
| Best Used For | Budget-restricted legacy policies | Comprehensive structural protection |
Under an Actual Cash Value policy, if a 10-year-old roof is damaged by wind, the payout deducts a decade’s worth of depreciation, leaving you to cover a significant portion of the new roof costs. With Replacement Cost coverage, your insurer pays the cost to repair or replace the damaged items with new materials of comparable quality, minus your deductible. For extensive guidance on state-specific insurance terms, you can consult the ALDOI – Consumer’s Guide to Homeowners Insurance.
Severe Weather Risks and Environmental Factors in Marshall County

Living atop Sand Mountain in Albertville offers beautiful scenery and a tight-knit community, but our geographic position exposes Marshall County properties to distinct environmental hazards throughout the year.
Alabama is consistently ranked among the top states for severe weather claims, with approximately 1 in 20 insured homes filing a claim each year due to wind, hail, or tornado damage. Spring and late autumn frequently bring severe thunderstorms and tornadoes across the Sand Mountain plateau. Straight-line winds and hail can strip shingles, crack siding, and send heavy oak limbs through roofs within minutes.
Understanding how your policy treats storm damage is essential. Some property policies may feature separate deductibles for named storms or specific wind and hail incidents. Being familiar with roof damage and replacement guidelines helps ensure your roof remains fully insurable and that you are not surprised by unexpected out-of-pocket expenses when severe weather strikes.
Another local factor is our proximity to Lake Guntersville and surrounding low-lying creeks. Heavy seasonal rainfall can cause rapid surface water runoff and flash flooding on properties with poor drainage or near local tributaries. It is critical to recognize that standard homeowners policies specifically exclude flood damage caused by rising external water. Securing separate flood protection through the National Flood Insurance Program (NFIP) or private flood carriers is the only way to safeguard your residence against rising water.
Determining Rates and Maximizing Policy Value
Insurance carriers evaluate several specific rating variables when assessing a property’s risk profile in Marshall County. When evaluating regional insurance options, knowing how these factors influence your premium gives you greater control over your overall costs:
- Age and Structural Condition: Newer homes with modern plumbing, updated wiring, and modern roofs generally qualify for lower premiums because they are less susceptible to sudden pipe bursts, electrical fires, or minor storm damage.
- Construction Materials: Brick, masonry, and fire-resistant siding often receive more favorable rating credits than all-wood frame structures.
- Fire Protection Class: The distance of your home from the nearest municipal fire hydrant and responding fire station directly affects your rating classification. Homes within Albertville city limits benefit from strong municipal fire services, while rural Marshall County addresses may carry different rating tiers.
- Credit-Based Insurance Score: In Alabama, carriers use credit-based insurance scores alongside claim history to evaluate risk stability, meaning strong financial management can translate into lower policy rates.
Evaluating the Average Costs of Homeowners Insurance in Albertville, AL
The average cost of homeowners insurance across Alabama sits at roughly $2,159 annually, reflecting the state’s exposure to frequent convective storms and severe weather systems. In Albertville, the average annual premium is approximately $2,300. This benchmark reflects local construction labor costs, property values on Sand Mountain, and regional storm activity.
Recent economic trends, including inflation and higher material replacement costs, have driven dwelling replacement valuations higher across the state. Despite this, an estimated 12% of homeowners in Alabama currently have no homeowners insurance, leaving their properties exposed to devastating financial loss. Making sure your dwelling coverage keeps pace with current labor and material rates is essential to prevent being underinsured after a total loss.
Practical Ways to Save on Homeowners Insurance in Albertville, AL
Maintaining complete protection does not mean you have to overpay. Homeowners in Marshall County can take proactive steps to reduce their ongoing insurance costs while improving structural resilience:
- Fortified and Impact-Resistant Roofs: Upgrading to Class 4 impact-resistant shingles or building to IBHS Fortified standards can earn substantial premium discounts.
- Smart Home and Protective Devices: Installing centrally monitored burglar alarms, hardwired smoke detectors, smart water-leak shutoff valves, and deadbolts provides safety credits.
- Adjusting Deductibles: Choosing a higher out-of-pocket deductible—such as increasing from $1,000 to $2,500—lowers your regular annual premium. Ensure you keep your chosen deductible amount accessible in a dedicated emergency fund.
- Routine Property Maintenance: Trimming overhanging tree limbs away from your roofline and clearing gutters regularly prevents preventable claims that could impact your long-term loss record.
Taking time to explore your options by comparing local property quotes allows you to match your deductible and coverage limits to your household budget.
Local Building Codes, Regulations, and Navigating Property Claims
The City of Albertville enforces modern building codes designed to enhance structural wind resistance and fire safety. When rebuilding or performing major renovations after a loss, your property must adhere to current local building regulations. Including Ordinance or Law coverage in your homeowners policy helps cover the additional costs required to bring an older, damaged structure up to modern building code standards during a covered repair.
If severe weather or an unexpected household accident damages your property, handling the claim systematically ensures a smooth resolution:
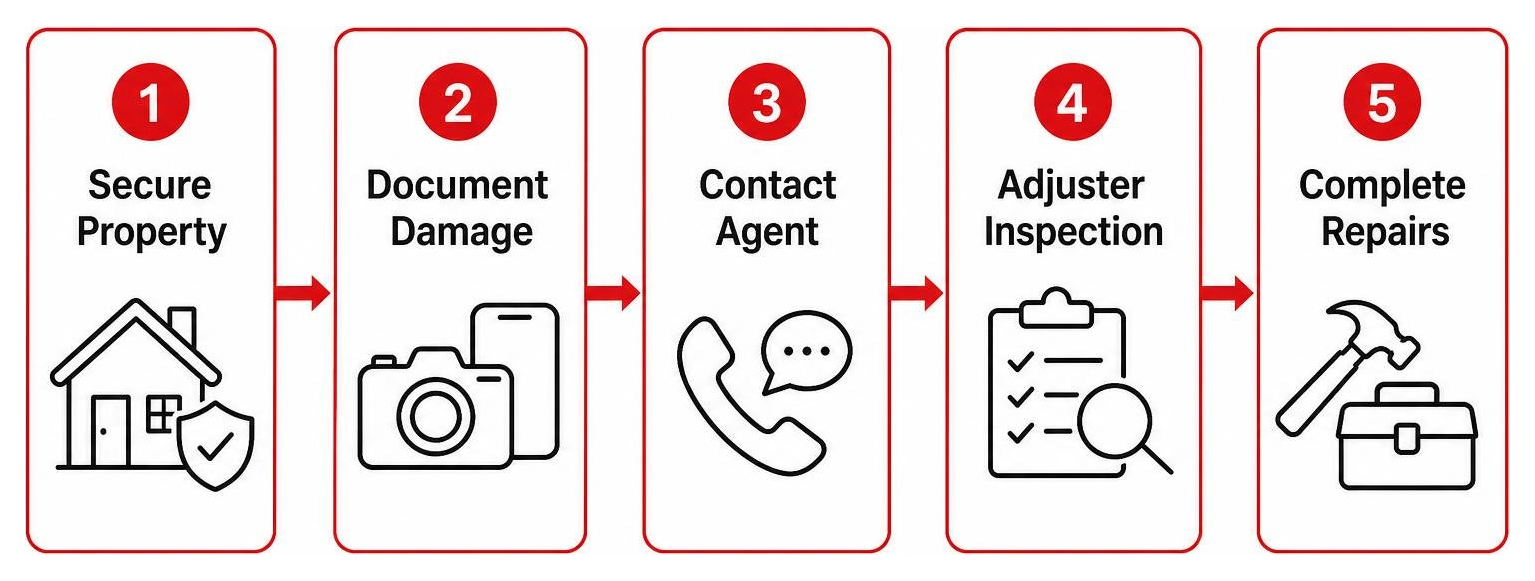
- Ensure Safety and Prevent Further Damage: Make sure your family is safe, and take immediate temporary measures to protect the home from secondary damage, such as placing a tarp over a leaking roof or shutting off the main water valve.
- Document Everything Thoroughly: Before moving debris or cleaning up, take clear photos and video footage of all damaged areas and affected personal property. Keep receipts for any emergency materials purchased.
- Contact Your Local Agent Promptly: Notify our local agency right away to initiate your claim and review your deductible requirements.
- Work Alongside the Claims Adjuster: Provide the adjuster with your inventory of damaged belongings and detailed photos during their physical inspection.
- Hire Licensed, Insured Local Contractors: Work with reputable, local repair professionals familiar with Marshall County building codes to complete your restoration work.
For additional answers regarding local claim handling and regional coverage rules, review our frequently asked North Alabama insurance questions.
Frequently Asked Questions About Home Insurance in Albertville
Does standard homeowners insurance cover flood damage near Lake Guntersville?
No. Standard homeowners insurance policies exclude damage caused by rising external water, surface runoff, or lake overflow. Property owners living near Lake Guntersville, low-lying creeks, or localized flood zones should purchase a separate flood insurance policy through the NFIP or a private flood insurer.
How often should Sand Mountain homeowners update their dwelling coverage?
You should review your dwelling coverage annually. Significant home improvements, such as remodeling a kitchen, building a deck, or installing a new outbuilding, increase your replacement cost. Regular policy reviews ensure your coverage limits match current regional construction costs.
What immediate steps should be taken after severe wind or hail damage?
First, ensure that your property is safe to enter. Take comprehensive photographs and videos of all damaged structures and belongings before beginning cleanup. Mitigate further damage by boarding broken windows or tarping exposed roof sections, save all temporary repair receipts, and contact your insurance provider immediately to open a claim.
Conclusion
Protecting your Albertville home requires a clear understanding of regional storm patterns, construction replacement costs, and policy terms. As a local Alfa Insurance provider, The Hornbuckle Agency serves multiple Alabama communities, including Albertville, Guntersville, Boaz, Arab, Geraldine, Crossville, Collinsville, Horton, and Douglas. We take pride in delivering personalized risk education to help you secure the right coverage for your lifestyle.
Whether you need residential dwelling coverage or comprehensive farm and residential property protection, our team is here to guide you. Contact us today to schedule a comprehensive property review and ensure your home is fully protected against whatever the North Alabama weather brings.
